 When was the last time you sat down and read your company’s retirement plan document? Not the enrollment materials or your quarterly statements. I’m talking about the actual plan document, the one that spells out the rules for how your retirement plan is supposed to operate.
If you’re drawing a blank, you’re probably not alone. Retirement plan documents aren’t exactly what most business owners reach for when they’re looking for a good read. But, with some important amendment deadlines approaching, now might be a good time to dust yours off.
SECURE 2.0 Is Back on the To-Do List
Remember the SECURE 2.0 Act? That thing that became law back in December 2022? It introduced over 90 changes related to retirement plans. Some of them took effect almost immediately, while others have been phased in over the last several years.
Fortunately, the IRS recognized that updating plan documents takes time and gave employers and plan providers some breathing room. For most of the SECURE and SECURE 2.0 changes, that breathing room ends on December 31, 2026.
This is where things get interesting. For several years, your plan may have been operating under different rules than those reflected in your written plan document. If you haven’t kept track of the changes you’ve implemented, it will be difficult to accurately update the plan document to reflect them. This is where things can get a little messy.
When the Document and Reality Don’t Agree
Let’s look at a few examples of how this can happen.
Example 1: You added a feature but forgot about the paperwork.
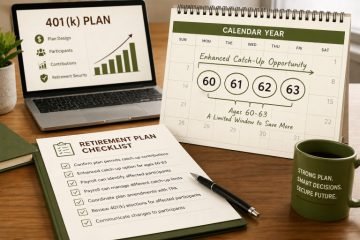
Let’s say you decided to allow employees ages 60–63 to make the higher catch-up contributions permitted under SECURE 2.0 beginning in 2025. Payroll was updated. The recordkeeper was ready. The contributions were processed correctly.
So everything’s good, right?
Not necessarily. Was that decision communicated to your plan document provider so the feature can be properly reflected in the plan’s amendments? “Everyone knows” is not a viable substitute for proper documentation.
Example 2: Your plan counts bonuses, but payroll doesn’t.
Suppose your plan document says bonuses are included in pay when calculating employer matching contributions. Seems straightforward, except your payroll system has been calculating the match using regular pay only. Nobody intentionally changed the rules. Nobody even realized there was a difference. But now, some employees may have received less match than they should have.
This isn’t specifically a SECURE 2.0 issue, but it’s a great (and common) example of how a small disconnect between your plan document and your payroll can create an unexpected, and potentially expensive, problem.
Example 3: The rules changed, but your procedures didn’t.
SECURE and SECURE 2.0 changed the age at which required minimum distributions (RMDs) generally must begin for certain participants.
But what happens if your procedures still reflect the old rules for processing the plan’s RMDs? You could end up processing these distributions incorrectly. If the rules change but your procedures don’t, everyone involved may continue to do things the way they’ve always done them. Which, unfortunately, is wrong.
Remember that, sometimes, “the way we’ve always done it” is exactly what needs another look.
An Amendment Isn’t a Magic Eraser
Here’s an important distinction.
If your plan has been operating correctly under a SECURE 2.0 provision and the document simply needs to catch up, adopting the appropriate amendment by the applicable deadline may be all you need to do. But if your plan hasn’t been operating correctly, signing an amendment doesn’t automatically make the problem go away.
Looking at example 2 from the previous section, if you’ve been calculating matching contributions using the wrong definition of compensation, you may have an operational error that requires a separate correction. In other words, updating the plan document and correcting how the plan has been administered are two different things.
That’s why we believe reviewing plan operations and reviewing plan documents should go hand in hand.
So, What Should You Be Doing?
You don’t need to become an expert in retirement plan documents and handle this on your own. That’s why you have your TPA on speed dial.
You just want to make sure you know:
- Which SECURE and SECURE 2.0 provisions apply to your plan?
- Have you implemented any of the optional features that need to be reflected in your document?
- Have your payroll and administrative procedures been updated to match the amended plan document?
- Who needs to sign the amendments and when do they need to be signed?
Your plan document provider or TPA should be able to help you determine which provisions and deadlines apply to your particular plan.
The Bottom Line
Your retirement plan document isn’t just paperwork that gets signed and filed away. It’s the instruction manual for how your plan is supposed to work. Even the best manual doesn’t do much good when everyone is playing by a different set of rules.
The approaching amendment deadlines offer a great opportunity to make sure your plan document, payroll system, and day-to-day procedures are all on the same page.
Sometimes a second look today can save a lot of headaches tomorrow.